Deutsche Bank Faces Scrutiny Over Alleged Compliance Failures and Risky Clients
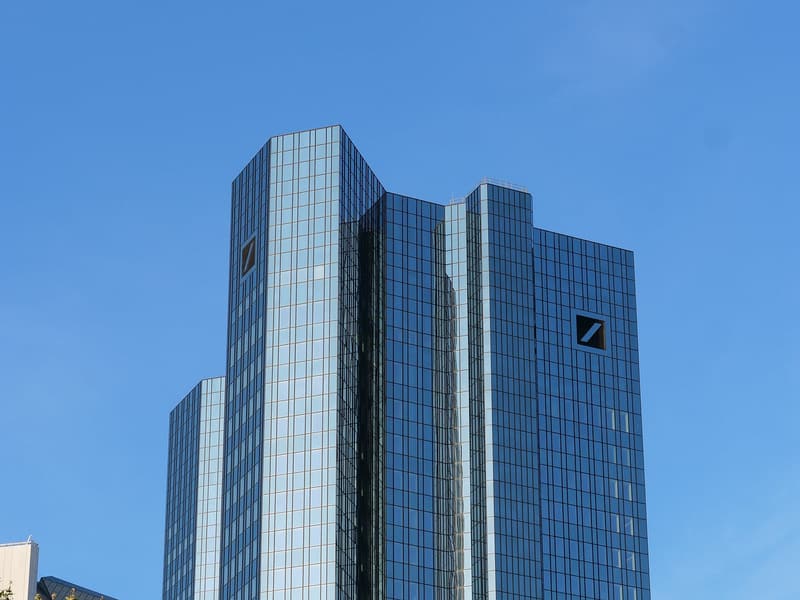
Representative photo · Photo: Leonhard Lenz / Wikimedia Commons, CC0
A major investigation into leaked internal documents suggests Deutsche Bank repeatedly ignored compliance warnings to prioritize profits from high-risk clients.
A recent international investigation has placed Deutsche Bank under intense scrutiny after a massive leak of internal data suggested the lender systematically overlooked compliance risks to maintain profitability. The findings, which have triggered a 4% decline in the bank's German-listed shares, allege that the institution repeatedly disregarded internal warnings regarding its dealings with controversial figures, including high-profile Russian oligarchs. As investors monitor the latest Deutsche Bank news, these reports highlight a pattern of prioritizing business growth over regulatory safeguards.
Internal Warnings and Risk Management
The investigation, involving multiple global media outlets, analyzed 15 million internal files. These documents reportedly show that the bank ignored concerns raised by its own compliance officers, even after the institution had previously been implicated in laundering billions of dollars for Russian entities between 2010 and 2015. Reports suggest that under CEO Christian Sewing, the bank pursued a strategy that included maintaining relationships with a list of "most sensitive clients," which allegedly featured approximately 50 corporate entities linked to the Kremlin, such as Gazprom and Sibur, as well as individuals like Oleg Deripaska.
Deutsche Bank allegedly ignored internal compliance warnings to prioritize profits from high-risk clients.
Beyond its Russian operations, the bank is facing renewed questions regarding its historical relationship with the late sex offender Jeffrey Epstein. Investigations indicate the lender processed nearly $600 million in suspicious payments linked to Epstein, a figure significantly higher than previously disclosed. Additionally, the bank was accused of accidentally leaking tax documents belonging to former U.S. President Donald Trump, a matter it reportedly kept from the White House. The bank stated it does not comment on specific client relationships and noted that it severed ties with Trump in 2021.
Bank Response
In a public statement, the bank asserted that it has undergone a fundamental transformation. It noted that the issues raised date back many years and that it has invested €7 billion in its control environment between 2019 and 2025. The institution emphasized that it remains committed to fostering a culture of integrity while protecting confidential client information.
Why it matters
These revelations represent a significant challenge for the bank as it attempts to move past years of scandal and reputational damage. For global stakeholders, including those in India where the bank maintains a presence, the reports underscore the ongoing tension between aggressive profit-seeking strategies and the necessity of robust regulatory compliance in the international financial sector.
Sources
More like this
Santander UK allows staff to count leave as office attendance
Ikea Halts UK Store Expansion Plans Citing High Business Tax Costs
Modella Capital Explores Sale of TG Jones Following Former WH Smith Store Overhaul