Canada Proposes Stablecoin Act Access for Banks via Separate Subsidiaries
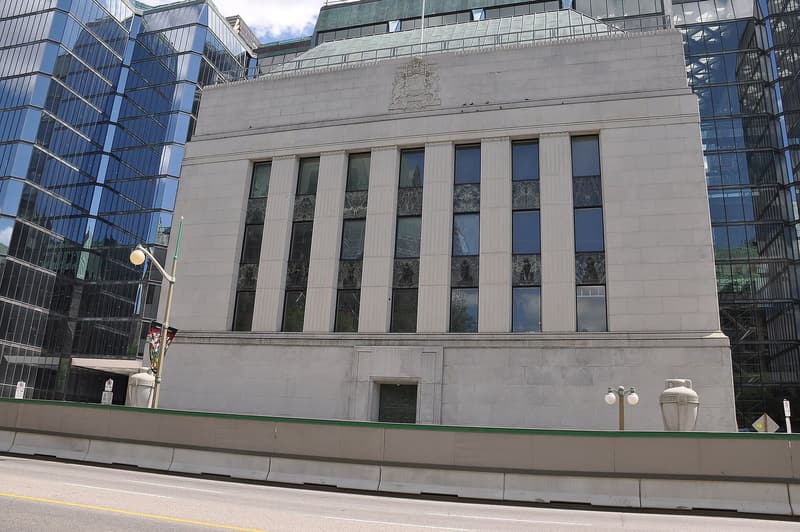
Representative photo · Photo: shankar s. from Dubai, united arab emira / Wikimedia Commons, CC BY 2.0
Canada's federal budget proposes allowing banks and foreign institutions to issue stablecoins through separate subsidiaries under the Stablecoin Act.
This is news, not investment advice. NexVani Media is not a SEBI-registered investment adviser and does not recommend buying or selling any security. Do your own research or consult a registered adviser before investing.
Canada's November 5 budget outlines plans to permit federally regulated financial institutions to issue stablecoins, provided they operate through separate subsidiaries. This legislative adjustment brings bank-backed issuers under the existing Stablecoin Act alongside nonbank entities. The proposals prohibit traditional banks from issuing stablecoins directly, instead requiring them to route such activities through non-financial-institution subsidiaries governed by the framework.
Under the proposed rules, stablecoins issued by these entities will remain separate from publicly insured deposits. Sections 33 and 34 of the legislation explicitly prevent covered stablecoins from being classified as deposits, publicly insured instruments, or government-guaranteed assets. Furthermore, the framework mandates that parent company involvement will not convert any digital token into an insured savings balance, ensuring clear boundaries between traditional banking products and digital assets.
The legislative annex also proposes amending the Bank Act, Trust and Loan Companies Act, and Insurance Companies Act to enforce direct issuance prohibitions for federally regulated financial institutions. Additionally, Budget 2026 plans to extend the regulatory framework to foreign financial institutions that operate outside Canadian prudential supervision, aiming for consistent treatment across all types of issuers.
Operating safeguards outlined in the legislation require stablecoin issuers to maintain reserves equal to at least the total outstanding face value. These reserve assets must undergo qualified custody, segregating them and protecting them from the creditor claims of issuers and custodians, excluding holders' redemption rights. The framework also stipulates that tokens must be redeemable at face value in the currency they track.
The Bank of Canada is designated to oversee registration for non-financial institution issuers, monitor issuance and redemption risks, supervise compliance, and exercise enforcement powers. While the Stablecoin Act received royal assent on March 26, its operational provisions await implementation orders from the Governor in Council, with officials targeting a commencement window in fall 2027.
Bank-issued stablecoins in Canada must operate through separate subsidiaries and will lack public deposit insurance.
Why it matters
The proposed regulatory adjustments redefine how traditional financial institutions engage with digital currencies in Canada. By requiring separate subsidiaries and explicitly stripping deposit guarantees, the framework establishes a distinct boundary between conventional banking safety nets and private digital assets, influencing compliance and operational strategies for financial entities preparing for the 2027 rollout.
Sources
More like this
HIVE Digital Technologies Reports Higher Bitcoin Production Amid Revenue Decline
Amundi Issues Tokenized Amundi European Equity Fund on Ethereum
Anthropic Releases Claude Fable 5.2 and Mythos 5.2 With High Autonomous Capabilities